Client Snapshot
-
 Building Type
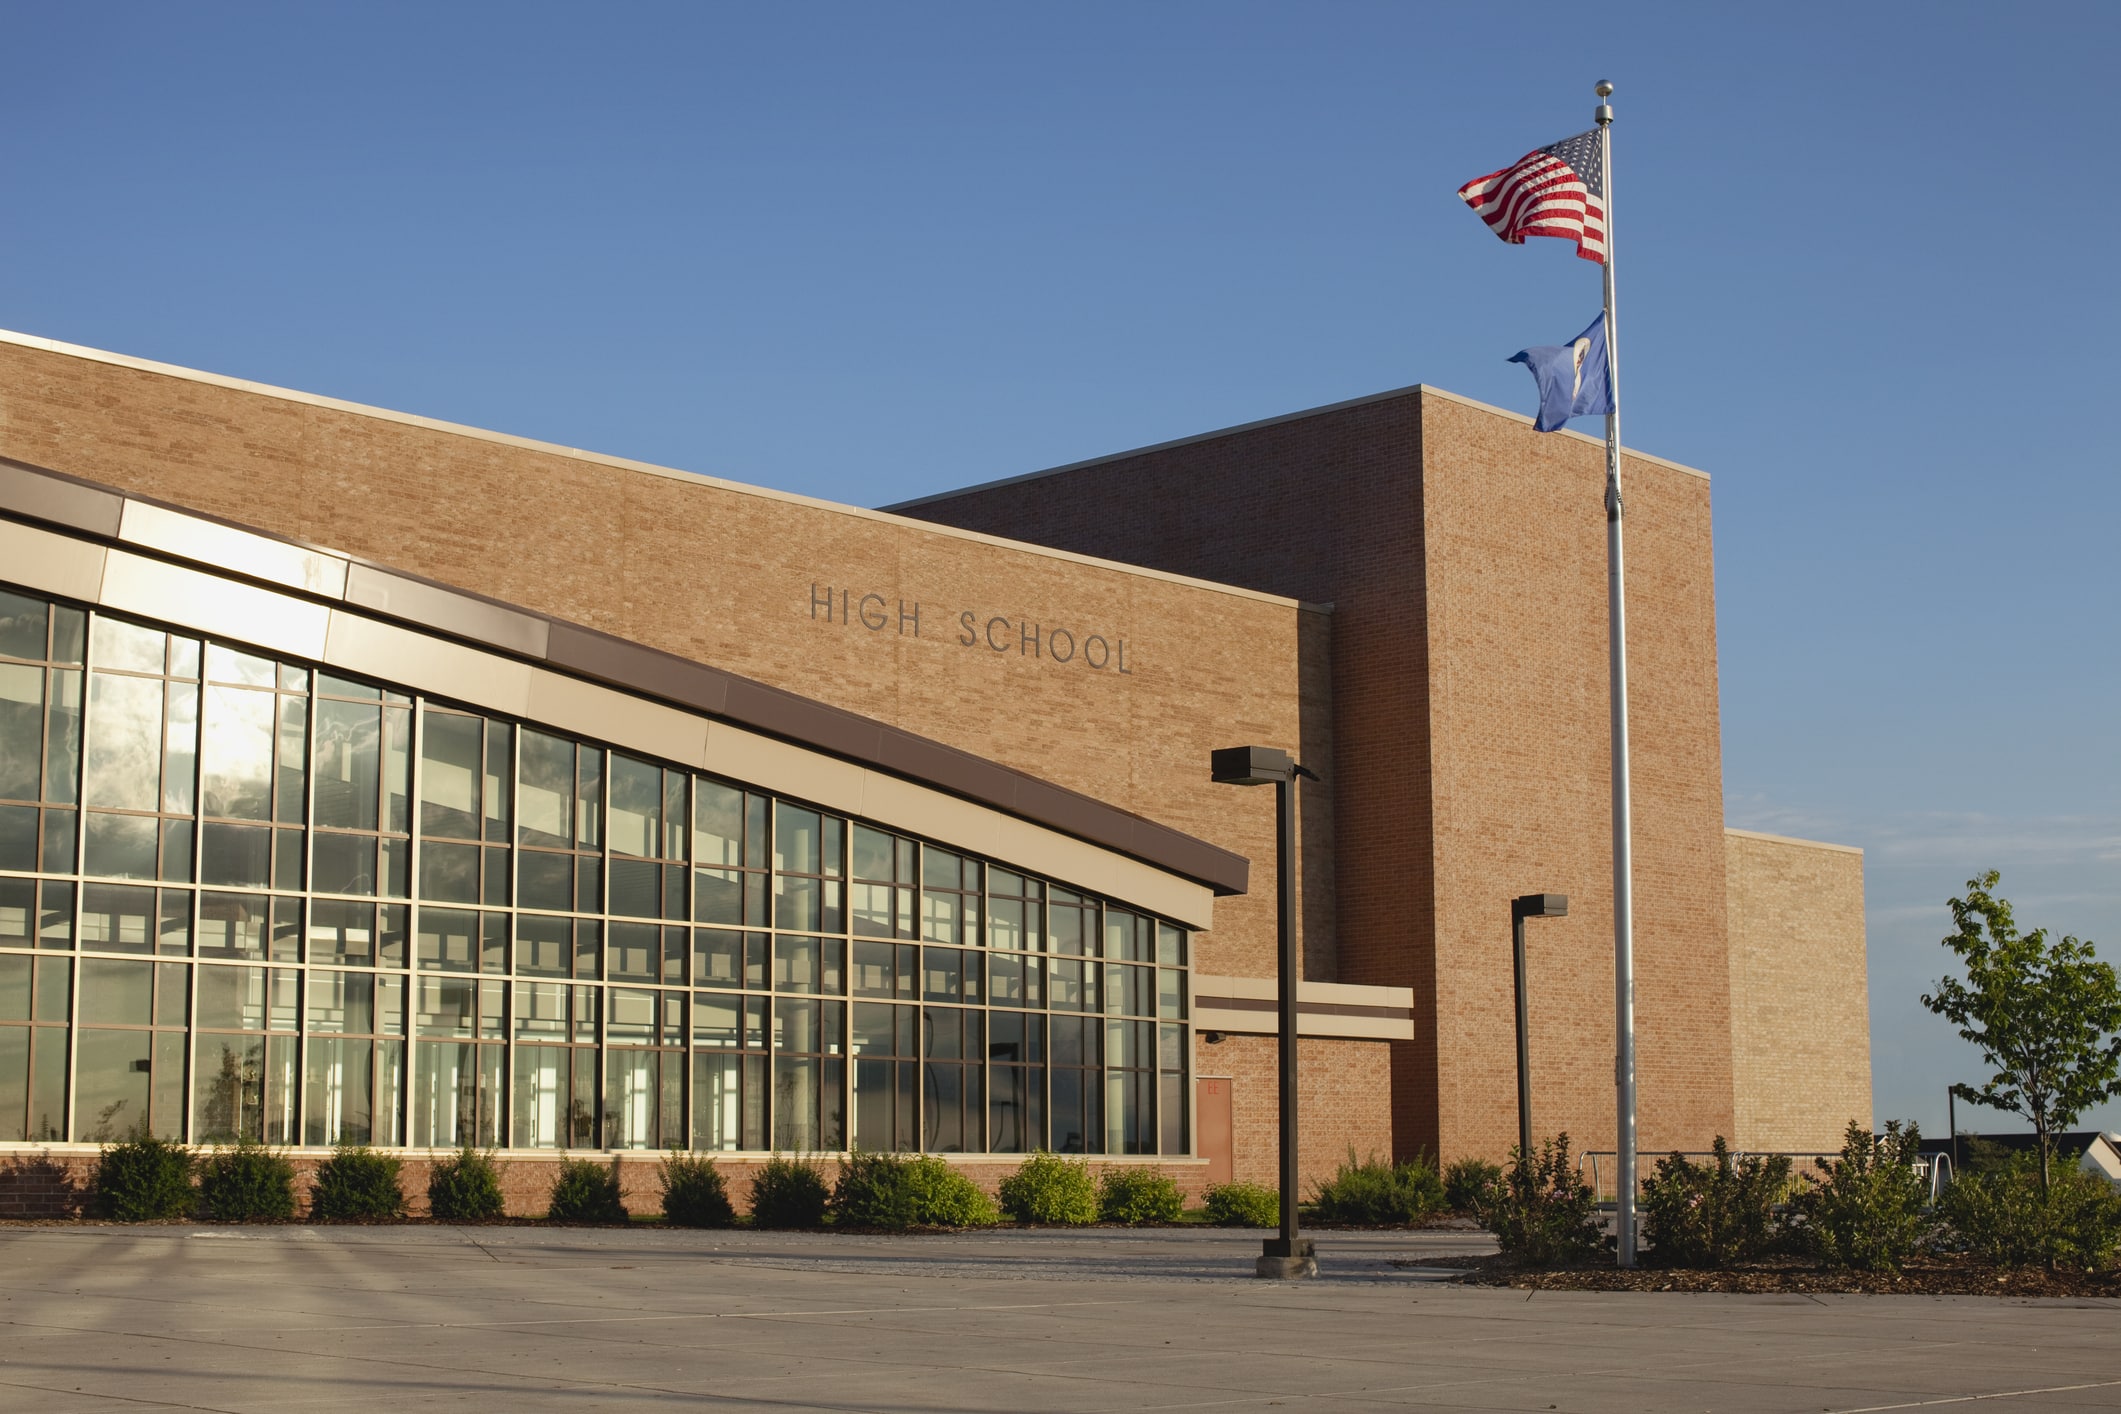
High School & Technology Center
-
 Location
Albany, KY
-
 Study
Investment Tax Credit (ITC)
-
 Project Objective
Geothermal Tax Credit
Approach & Results
Client Profile
A tax-exempt public school is undertaking an approximately $65 million construction project for a new high school and technology center in Albany, Kentucky. The project includes a geothermal HVAC system that will serve both buildings through a two-phase construction process. The school’s CPA engaged McGuire Sponsel’s Fixed Assets team before construction began to evaluate the geothermal system for the Investment Tax Credit (ITC) and identify opportunities to maximize the available credit.
Process
By becoming involved before construction, our Fixed Assets team was able to strategically evaluate the two-phase project and help organize the geothermal system’s qualifying costs. Phase I includes the wellfield and central pumping infrastructure integrated with the new high school, while Phase II connects the technology center to the geothermal system.
Our team performed a detailed cost analysis to identify qualifying geothermal components, including well drilling, piping, HVAC units, and associated plumbing and electrical work, while separating nonqualifying construction costs. Qualifying indirect costs, including applicable insurance and engineering expenses, were proportionally allocated to the geothermal system.
The team also evaluated the project for applicable ITC bonus opportunities. In addition to the 30% credit applicable to the project, the development qualifies for a 10% Energy Community bonus and a 10% Domestic Content bonus, resulting in a projected effective ITC rate of 50%.
Study Results
Based on current project estimates, approximately $5 million in direct costs and $200,000 in allocated indirect costs are expected to qualify for the ITC, resulting in approximately $5.2 million in total qualifying costs.
At the projected 50% effective ITC rate, the project is expected to generate a total Investment Tax Credit of approximately $2.6 million. As a tax-exempt entity, the public school can monetize the credit through the Direct Pay provisions of Section 6417.
-
$2.6 Million
Investment Tax Credit
Contact Us
Wondering whether your client’s energy project may qualify for the Investment Tax Credit?
Reach out to McGuire Sponsel to discuss your client’s project and potential tax credit opportunities.
Additional Resources
-
 case studiesFixed Asset ServicesAugust 13, 2026
Portland Mixed-Use Development Cost Segregation Study
by Dave McGuireA cost segregation study for a $195 million mixed-use development identified more than $25 million in shorter-life assets, significantly increasing...
-
 webinarsAlliance NetworkAugust 12, 2026
Summer 2026 Specialty Tax Webinar Series
by McGuire SponselJoin us for six technical webinars designed to help CPA firms navigate evolving compliance requirements, uncover overlooked planning opportunities, and strengthen...
-
 case studiesFixed Asset ServicesAugust 10, 2026
California Auto Dealership Cost Segregation Study
by Dave McGuireA cost segregation study of a recently acquired $48 million California auto dealership reclassified 28% of its depreciable basis and...
-
 blogAlliance NetworkJune 18, 2026
Trump’s Cannabis Rescheduling Opens the Door to New Tax Planning Opportunities
by David Seibel, EAFederal cannabis rescheduling could unlock valuable tax planning opportunities for qualifying medical marijuana businesses. Learn what Section 280E changes could...